For first-time home buyers in Panama City Beach, FL, the median sale price sits around $380,000 as of mid-2026. Inventory is healthy right now - 857 homes available, translating to about 7.9 months of supply.
That sticker price, though, is only the starting point. To know what you can actually afford here, you have to layer in local insurance rates, property taxes, and current interest rates before you land on a real monthly payment number. Get those figures straight first, and you'll shop with a lot more confidence.
Current Home Prices and Market Conditions in Panama City Beach
This is a buyer's market. Homes are sitting on the market for roughly 101 days before going under contract, and sellers know it - properties are closing at about 95.6% of list price. Only about 3.7% of homes are selling above asking, so you're not walking into a war zone every time you make an offer. You have room to negotiate without blowing your budget just to win.
What Homes Cost Right Now
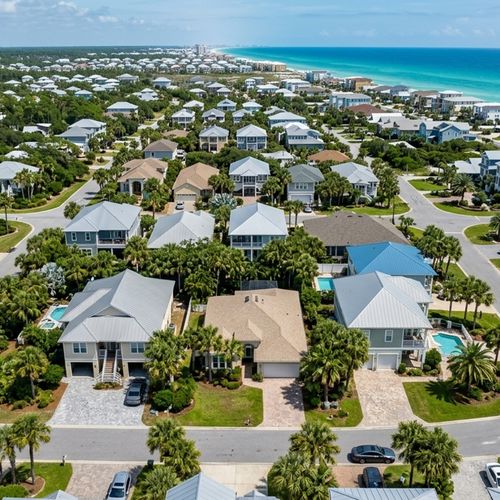
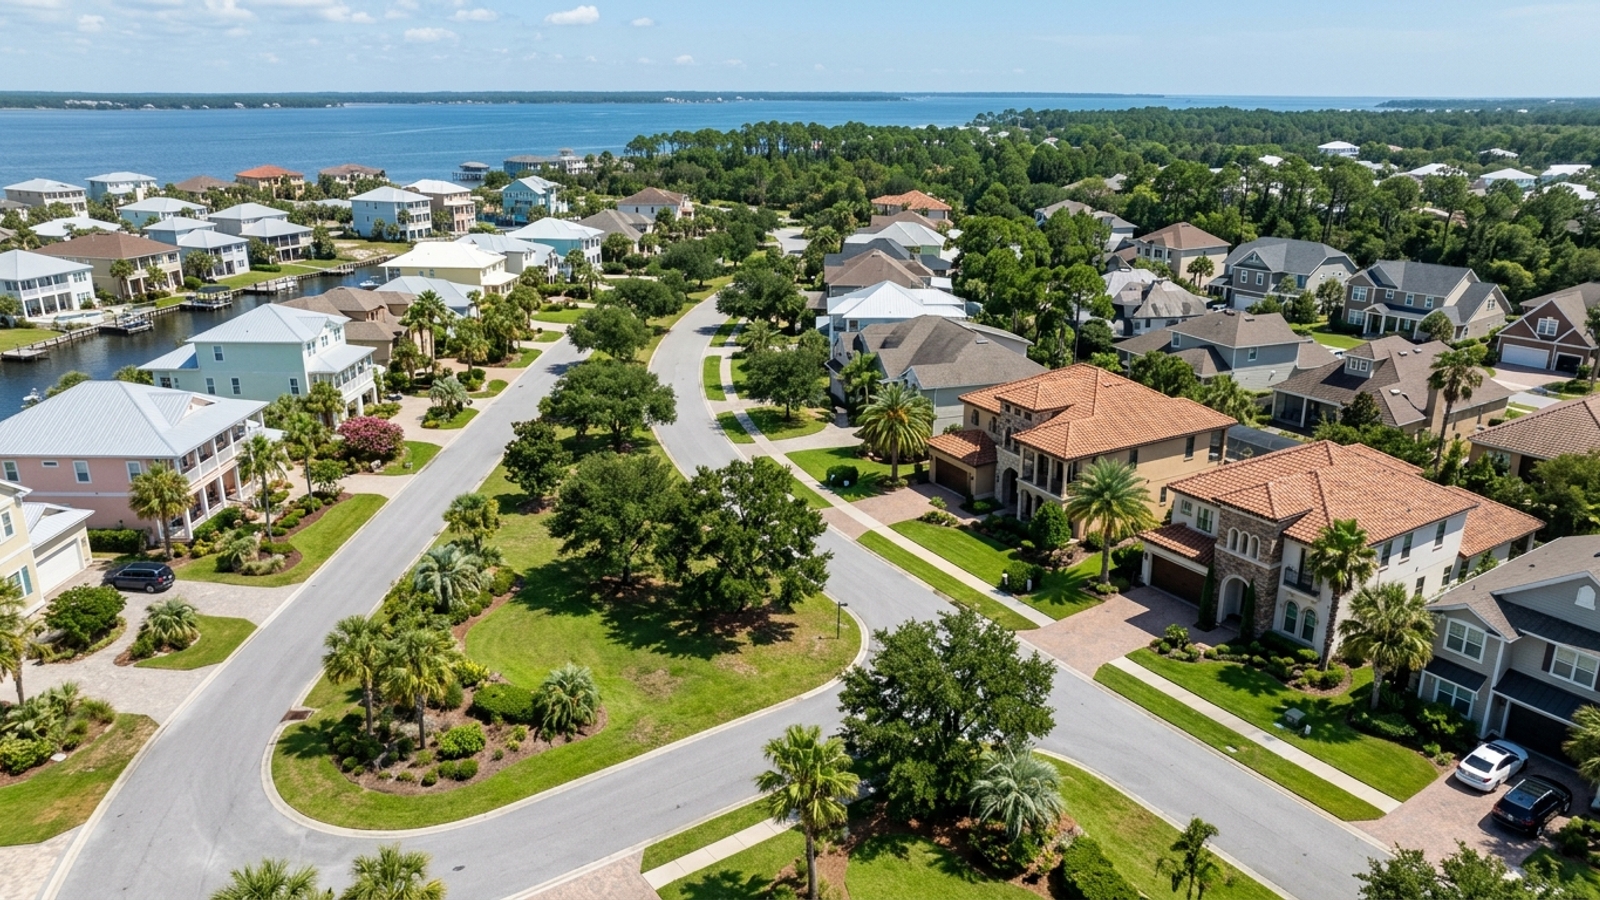
The median sale price is near $380,000, but the specific number you'll see depends on property type and location. Zillow puts the average home value closer to $413,312; Houzeo reports a median around $355,000. That gap isn't random - it reflects the spread between modest inland homes and premium coastal properties. If you're shopping near the water, plan on the higher end of that range.
Factoring in Today's Mortgage Rates
Florida rates in late August 2026 are running between 6.5% and 6.95% on a 30-year fixed. MonitorBankRates recently reported 6.528%; Experian put averages closer to 6.95%. If a shorter term works for you, 15-year fixed rates are averaging around 6.0% to 6.15%. Every fraction of a point matters when you're working backward from a monthly payment ceiling, so it's worth shopping lenders before you lock.
Using the 28/36 Rule to Set Your Budget
Lenders use the 28/36 rule to measure whether your income can carry your debt load. It's a two-part test, and underwriters lean on these debt-to-income (DTI) ratios when they're deciding whether to approve your mortgage.
Calculating Your Maximum Monthly Payment
The "28" is your front-end ratio - your total housing payment (principal, interest, taxes, and insurance, or PITI) shouldn't exceed 28% of your gross monthly income. On a $100,000 annual salary, your gross monthly income is $8,333, which puts your ceiling at $2,333 a month.
Accounting for Your Current Debt
The "36" is your back-end ratio: all of your monthly debt obligations combined - housing payment, car loans, student loans, minimum credit card payments - capped at 36% of gross income. With that same $8,333 monthly income, you're looking at a $3,000 ceiling across everything. If your existing debts are already eating a big chunk of that, you'll need to target a lower purchase price to keep the math working.
Local Expenses to Factor Into Your Monthly Payment
Your mortgage payment is more than principal and interest. In Florida, property taxes and insurance typically roll into that same monthly bill, and coastal properties carry meaningfully higher ongoing costs than homes further inland. Buyers who don't account for this upfront often find themselves stretching past a comfortable payment on a house that looked fine at first glance.
Budgeting for Bay County Property Taxes
Bay County uses a millage rate of 12.28 mills. On a $350,000 home with a homestead exemption, that works out to roughly $3,812 per year - an effective rate of about 1.08% to 1.09%, per Momentum Realty and Ownwell. For a specific listing, run the numbers through the Bay County Property Appraiser and Tax Collector websites rather than relying on estimates.
Wind, Flood, and Homeowners Insurance
This is where Panama City Beach gets expensive in a hurry. Clovered reports an area average of $2,685 annually, but newer estimates for coastal homes run considerably higher. Bridgeway Insurance cites a typical range of $2,000 to $5,000 a year; Jessica Lyng Insurance puts the top end at $4,500 to over $8,200 annually. Wind exposure and storm surge risk are driving those numbers.
Get insurance quotes before you get attached to a property. Not after.
Homeowners Association Fees
A lot of neighborhoods and condo complexes in Panama City Beach carry mandatory HOA fees - monthly or quarterly dues that cover community maintenance, amenities, and sometimes exterior insurance. Lenders fold these fees directly into your DTI calculation. High HOA dues shrink the loan amount you can qualify for, so you'll want that number before you run affordability figures on any specific unit.
Upfront Costs to Close the Deal
Before you get the keys, you need cash on hand for two things: your down payment and closing costs. The exact amounts depend on your loan type and the final purchase price, but there's real assistance available if you need help covering either one.
Down Payment Requirements
You don't need 20% down. Conventional loans can go as low as 3% to 5%; FHA loans require 3.5% minimum. On a $380,000 home, that 3.5% comes to $13,300. If you put down less than 20%, you'll pay private mortgage insurance (PMI) on top of everything else - factor that into your monthly payment estimate.
State and Local Assistance Programs
The Florida Housing Finance Corporation runs a couple of programs worth knowing about. The Florida Assist Second Mortgage offers up to $10,000 as a deferred loan at 0% interest. The Florida Hometown Heroes Loan Program provides up to $35,000 for eligible workers and military members. Bay County also participates in the State Housing Initiatives Partnership (SHIP) program, and those local funds can sometimes be stacked with state programs to put a significant amount of assistance within reach.
Planning for Closing Costs
Closing costs typically run 2% to 5% of the total loan amount, covering the appraisal, title search, loan origination, and recording taxes. Budget for several thousand dollars on top of your down payment. Sellers will sometimes agree to cover a portion during negotiations - it doesn't hurt to ask.
Frequently Asked Questions
What salary do I need to make to afford an average home in Panama City Beach?
Your exact required salary depends on your interest rate and local insurance costs. Lenders will apply the 28/36 rule, and your total monthly payment - Bay County taxes and insurance included - needs to stay under 28% of your gross income.
How much should I budget for Florida wind and flood insurance when calculating my PCB housing costs?
It varies a lot depending on the home's location and storm surge exposure. Some estimates point to an area average around $2,685 a year, but coastal properties can run $4,500 to over $8,200 annually.
How do high condo HOA fees on the Gulf affect my maximum mortgage approval amount?
Lenders count HOA dues in your debt-to-income ratio. Higher monthly fees mean your lender will approve a lower loan amount to keep your total housing payment within the 28% limit.
Is it more affordable to buy a house inland instead of on the beach?
Generally, yes. Insurance premiums drop considerably once you're away from the coast - wind and storm surge risk is the main driver of those higher coastal rates, so inland properties are cheaper to carry on a monthly basis.
What down payment assistance programs are available to help me afford a primary residence in Bay County?
The Florida Assist Second Mortgage offers up to $10,000; the Hometown Heroes program goes up to $35,000 for eligible military and workers. Bay County's SHIP funds can sometimes be layered with those state programs.
Check out this article next